 GITEX Dubai
 Ai Everything
 LEAP26
 AI
 Saudi Arabia
 UAE
 Egypt
Egypt’s Dayra Wins FRA Digital Microfinance Licence to Scale Embedded Lending

3 min
Dayra has received a digital microfinance licence from Egypt's Financial Regulatory Authority.
It becomes the country's first licensed embedded digital microfinance provider.
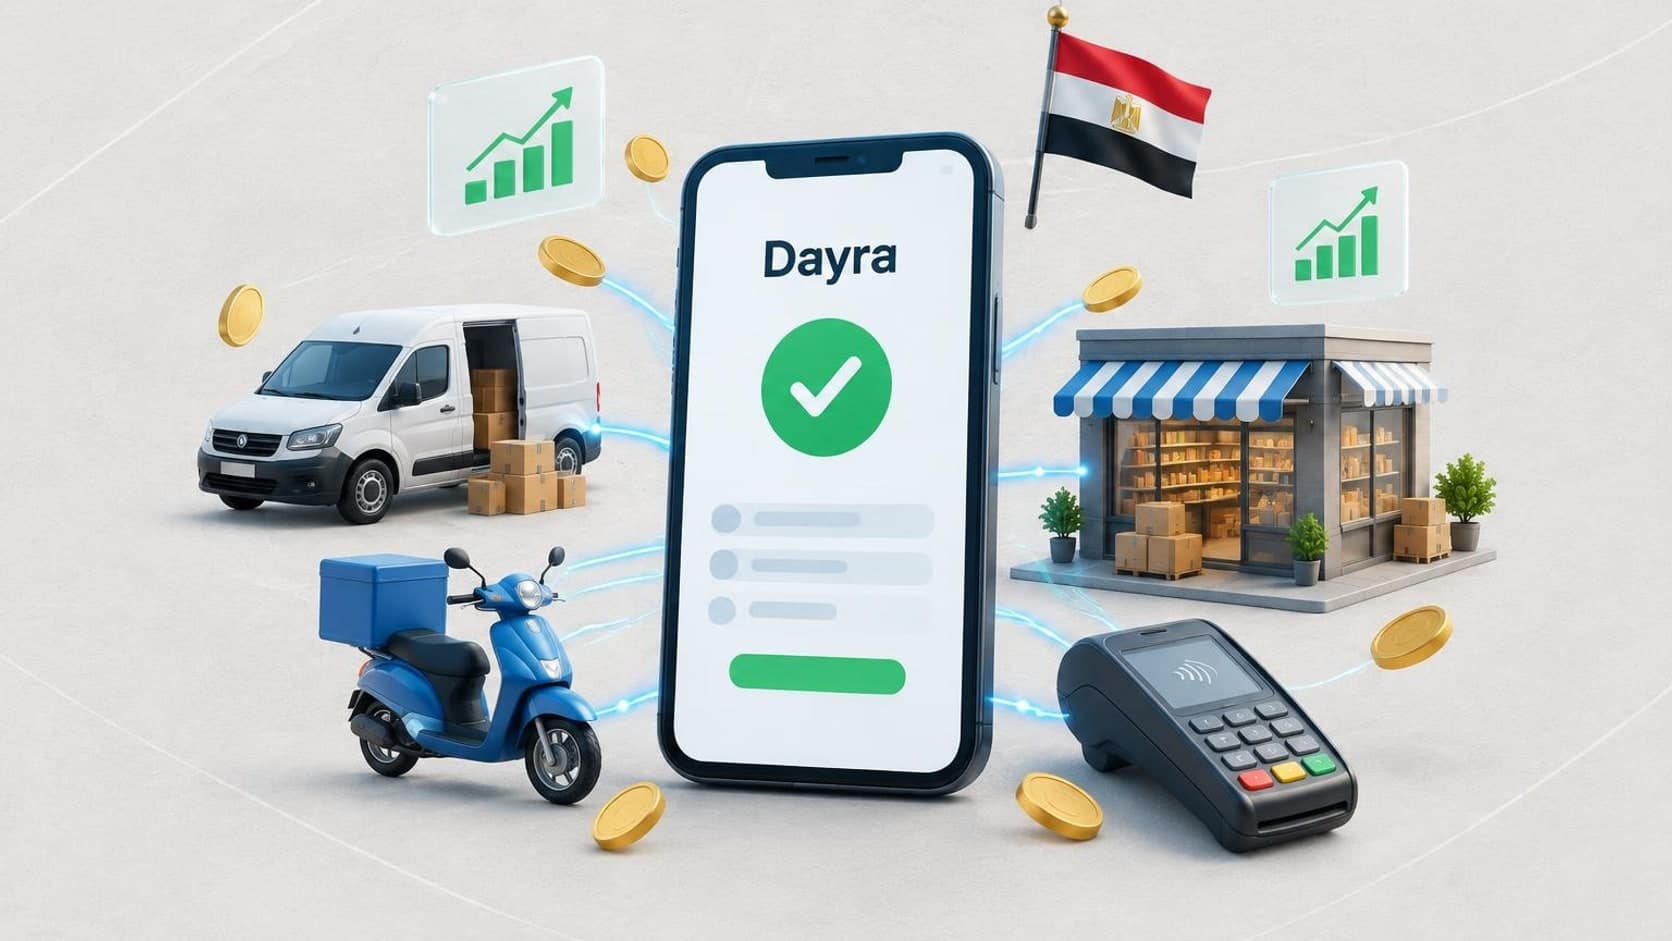
Financing is offered through marketplaces, gig platforms, logistics firms and payment gateways.
Credit checks rely on transactional and behavioural data from partner platforms.
Its next phase targets more micro-businesses and workers across Egypt.
Egyptian fintech Dayra has received a digital microfinance licence from the Financial Regulatory Authority (FRA), making it the country's first licensed embedded digital microfinance provider. The approval lets the company offer financing directly inside the digital platforms that micro-businesses and gig workers already use every day.
That's a meaningful shift. For businesses and workers who sit outside the reach of traditional banks, getting financing can be a real barrier to growth, and often a bit of a faff even when it is available.
Founded in 2021, Dayra builds embedded financial infrastructure for businesses, their customers and their workforces. Rather than asking people to walk into a separate lender, it partners with B2B marketplaces, gig platforms, logistics companies and payment gateways, and plugs financing into the services those partners already run.
The new licence covers exactly that model. Dayra can now offer financing through existing digital platforms across those same categories, bringing credit closer to where its customers operate, sell and earn.
"This license allows us to scale a model we have been building for years: using technology and alternative data to make financing more accessible to the businesses and workers who need it most," said Omar Ekram, Co-Founder and CEO of Dayra.
The engine behind it is data. Dayra uses the transactional and behavioural data generated by borrowers' activity on partner platforms to build alternative credit assessments. In plain terms, instead of relying only on a formal credit history, it looks at how a micro-business or individual actually trades and earns on the platform, which helps it serve people with limited access to traditional financial services.
Its financing portfolio spans inventory financing, working capital, capital expenditure (CAPEX) financing and earned income access, which lets workers draw on wages they have already earned. All of it is aimed at underserved micro-businesses and workers across Egypt.
There's also an AI angle. Dayra is developing AI-native workflows using locally deployed models trained and reinforced with its own proprietary data. The aim is greater control over its data, models and AI infrastructure, in support of what the company describes as an AI-sovereign strategy for financial services.
For platform operators, the licence opens a practical door: they can integrate financing into their existing services rather than sending customers off to navigate separate financial institutions. That said, the real test will be how many partners take it up and how well the alternative credit models hold up at scale.
Around Arageek, we often talk about how embedded finance could reach people that banks have struggled to serve, and I reckon a licensed, regulated route for this model in Egypt is a useful step for the wider fintech sector. It also highlights the growing role of alternative credit assessment built on platform-generated data.
Dayra says its next phase will focus on extending access to financing for micro-businesses and workers through the platforms where they already operate, sell and earn.
🚀 Got exciting news to share?
If you're a startup founder, VC, or PR agency with big updates—funding rounds, product launches 📢, or company milestones 🎉 — AraGeek English wants to hear from you!

✉️ Send Us Your Story 👇